


Transition management for your operational due diligence in France.
Before signing, a fund or a foreign group needs an operational view from the shop floor: not just a financial audit. An industrial transition manager assesses the production assets, the organisation and the hidden employment-related risks of a French target in depth, on site.
Call back within 2 business hours · 3 targeted profiles within 72h · 100% industry
What a transition manager does in an operational due diligence
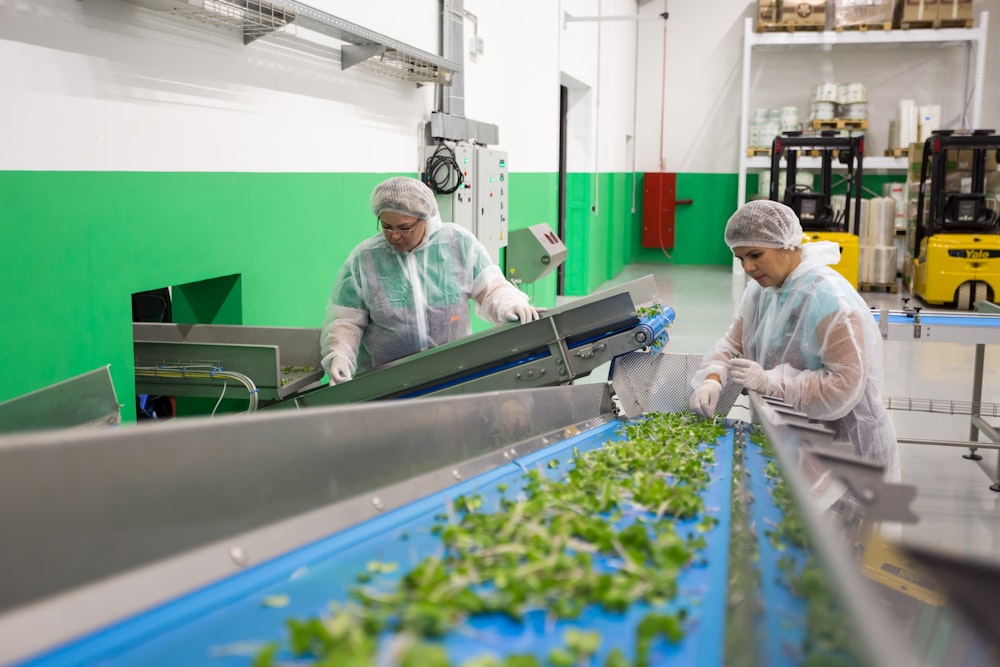
Financial and legal due diligence answer the question “what is the target worth”. They never answer the question “can this plant deliver the industrial plan in the business case”. That is the transition manager’s job: several days on site, interviews with the management line, observation of the real production flows, and a written diagnosis of the state of the industrial assets, the quality of the management team in place, the labour climate and the hidden risks no accounting document reveals. They work alongside the financial and legal advisers, strictly on the operational and human side, and report directly to the buyer: in English where required.
When investors call in a transition manager for due diligence
Three situations come up most often. A foreign fund acquiring an industrial site: the fund needs an independent operational opinion before the investment committee, on an asset none of its partners can audit technically. Buying a French competitor or supplier by a foreign industrial group that wants to check the reality of the shop floor against the seller’s sales pitch. Taking over a distressed site (secondary LBO, forced sale, insolvency proceedings) where deadlines are very short and an experienced industrial eye can avoid buying employment liabilities or obsolete equipment that a standard financial audit never catches.
The profile: who can run an operational due diligence
The profile has held a genuine industrial leadership role (site director, operations director or industrial director) and can therefore read a shop floor within hours: age of the machine base, real engagement levels in the teams, quality of middle management, undocumented cost drift. They know French employment law well enough to spot hidden liabilities (latent labour tribunal claims, unfavourable company-level agreements, understaffing masked by structural use of temporary workers). And they can present that diagnosis to a foreign investment committee or board, in professional English, with costed and prioritised recommendations rather than a descriptive report.
What head office should expect from the transition manager
The assignment starts with a precise brief: scope to be audited (one site or several), the deadline set by the transaction timetable (often 2 to 4 weeks), and the reporting format the investment committee expects. The transition manager must produce a structured, prioritised report: deal-breakers, risks to be reflected in the price or in the warranty package, and post-acquisition improvement opportunities. They must stay strictly independent of the seller and have no ties to the management team in place, so the opinion is unbiased. If the deal closes, the same transition manager can then be mandated to run the first hundred days of integration: a continuity many foreign owners value, because it avoids losing the memory of the original diagnosis.
A typical assignment
The context: a Dutch industrial investment fund is negotiating the acquisition of a French precision engineering subcontractor with 220 employees, a tier 2 aerospace supplier, as part of a build-up strategy. The investment committee requires an independent operational opinion before the agreement is signed. The stakes: the standard financial audit says nothing about the real condition of the machine base (40% of it more than 15 years old) or about the labour climate, while a company-level agreement is due to expire in six months. The assignment: the transition manager works for three weeks with full access to the site, alongside the financial and legal due diligence teams. How it ran: week 1, review of the machine base and production indicators, plus interviews with middle management; week 2, analysis of the labour climate, company-level agreements and latent tribunal exposure with a local employment lawyer; week 3, report writing and presentation to the investment committee in Amsterdam, in English, with a prioritised risk matrix. The outcome: three major risks identified (machine under-investment costed at €1.8m, a company-level agreement to renegotiate, dependence on two customers for 70% of revenue), all reflected in the final price negotiation and in the signed warranty package.
When to bring in a transition manager for your due diligence
Three signals should trigger the call: a letter of intent already signed with an exclusivity clause and a tight closing timetable, an investment committee asking for an independent operational opinion before the final decision, or a deal where the standard financial audit does not cover the industrial assets or the labour climate in any depth.
The earlier the intervention happens in the process (ideally as soon as the letter of intent is signed) the more the transition manager has time to take the diagnosis to the bottom before the closing timetable accelerates. MT-Transition calls back within 2 business hours and presents 3 targeted profiles within 72 hours.
Sectors covered
Related assignments
Frequently asked questions
How long does an operational due diligence take?
Usually 2 to 4 weeks, depending on the size of the site and the number of establishments to cover. A shorter window is possible but reduces the depth of the diagnosis.
Does the transition manager replace the financial and legal due diligence?
No, they work alongside those audits, strictly on the operational and human side that the others do not cover in detail: condition of the industrial assets, labour climate, quality of the management line.
Can the seller refuse site access for this due diligence?
Access is usually framed by the letter of intent. Restricted or late access is in itself a signal to factor into the risk analysis.
Can the same transition manager then run the post-acquisition integration?
Yes, and it is recommended in most cases: continuity avoids losing the memory of the original diagnosis and speeds up the first hundred days.
Can the report be delivered in English?
Yes: the debrief is delivered in whichever language the investment committee or the board at head office expects.
Secure your acquisition before you sign. Let’s talk today.
Call back within 2 business hours · 3 targeted profiles within 72h · 100% industry
See also